How to Get a Fidelity 401k ☎ +1(888)-358-1140 Withdrawal?
A Fidelity 401k Withdrawal allows eligible retirement plan participants to access money saved through an employer-sponsored 401(k) account. Whether you need funds after leaving a job, want to cover an unexpected financial emergency, or are preparing for retirement, understanding the withdrawal process can help you make better financial decisions.
Many people have questions about how to withdraw money from a Fidelity 401(k), how long the process takes, what taxes may apply, and whether early withdrawals are permitted. Others need assistance with a Fidelity Investments 401k Withdrawal because they cannot find the withdrawal option in their accounts.
The process depends on your employment status, age, retirement plan rules, available balance, and reason for requesting money. Not every participant can withdraw money whenever they want.
This guide explains how to request a Fidelity 401k withdrawal online, understand hardship withdrawals, cash out a retirement account, transfer funds to a bank, and contact Fidelity customer service for additional assistance.
What Is a Fidelity 401k Withdrawal?
A Fidelity 401k Withdrawal is the process of taking money out of a 401(k) retirement savings plan administered or serviced by Fidelity Investments.
A 401(k) is an employer-sponsored retirement plan that helps employees save money for their future. Employees can contribute part of their wages, and some employers provide matching contributions.
Depending on the account, contributions may be made with traditional pretax dollars, designated Roth contributions, or a combination of both.
The money generally remains invested until retirement, although certain circumstances may allow earlier access.
A withdrawal may be available when you retire, leave your employer, reach an eligible age, or qualify for a financial hardship distribution.
Unlike a retirement plan loan, a withdrawal generally does not have to be repaid. However, taking money out can reduce future retirement savings and may create tax obligations.
Fidelity administers many workplace retirement accounts, but the employer's plan document determines which distributions are available. Therefore, two employees with Fidelity 401(k) accounts may have different withdrawal options.
How to Get a Fidelity 401k Withdrawal Online?
If you are searching for How To Withdrawal From Fidelity 401k, the most convenient starting point is usually Fidelity's NetBenefits website.
NetBenefits allows eligible participants to review workplace retirement savings, check account information, and access available transaction options.
Step 1: Visit Fidelity NetBenefits
Open the official Fidelity NetBenefits website at www.netbenefits.com.
Sign in using your existing username and password.
If you have never registered, follow the website's registration instructions to establish online access.
Always confirm that you are using an official Fidelity website before entering personal or financial information.
Step 2: Select Your 401(k) Account
After logging in, locate your workplace retirement savings account.
Some participants have more than one account because they worked for different employers.
Choose the correct 401(k) plan and review the available account information.
Pay particular attention to your vested balance, any outstanding retirement plan loans, and your employment status.
Step 3: Find the Withdrawal Options
Look for a section related to loans, withdrawals, distributions, or taking money from your retirement account.
Depending on your plan, the relevant option may appear under account actions or a similar menu.
The exact wording and navigation can vary.
If the withdrawal option is missing, your employer's plan may restrict distributions, or your account may require additional eligibility verification.
Step 4: Choose the Withdrawal Type
Select the transaction that matches your circumstances.
You may see options for a retirement distribution, hardship withdrawal, rollover, or another permitted distribution.
Available choices depend on your specific plan.
For example, someone who recently left an employer may have different options from someone who is still working.
Step 5: Enter the Withdrawal Amount
If your plan permits the requested transaction, enter the amount of money you want to withdraw.
Before proceeding, review your available distribution balance.
The full account balance may not be available for withdrawal because of plan restrictions, outstanding loans, or unvested employer contributions.
Consider the tax implications before selecting a large amount.
Step 6: Review Payment Information
Depending on the plan and transaction, Fidelity may offer electronic bank transfer, mailed check, or other available payment methods.
Verify your bank details or mailing address carefully.
If your account requires bank verification, complete the requested security steps.
Step 7: Review Taxes and Submit the Request
Before submitting your Fidelity Investments 401k Withdrawal, review the distribution summary.
Pay attention to the requested amount, applicable withholding, estimated payment amount, and any information about additional taxes.
Confirm the transaction only after checking the details.
Keep a copy of the confirmation for your records.
Important: Submitting a withdrawal request does not guarantee approval. Fidelity or your employer's retirement plan administrator may need to verify eligibility or review supporting documentation.
Fidelity 401k Withdrawal Rules and Eligibility
Before starting a Fidelity 401k Withdraw transaction, it is important to understand the rules that control access to retirement savings.
Under federal law, 401(k) distributions are generally restricted until a qualifying event occurs.
Withdrawal After Age 59½
Age 59½ is an important milestone for retirement distributions.
Once you reach this age, distributions are generally no longer subject to the federal 10% additional tax for early withdrawals.
However, this does not mean every 401(k) plan must permit an immediate withdrawal while you are still employed.
Your plan's in-service withdrawal rules still apply.
Traditional pretax withdrawals are generally subject to ordinary income tax even after age 59½.
Withdrawal After Leaving an Employer
Leaving a job is generally a qualifying event that can make vested 401(k) funds available for distribution, subject to applicable plan rules and administrative requirements.
Participants may choose to leave their money in an eligible former employer's plan, transfer it to another retirement account, or withdraw the balance.
A cash withdrawal may result in taxes and additional penalties.
Withdrawal While Still Employed
Employees who are still working may have fewer withdrawal options.
Some employer plans permit hardship withdrawals, certain in-service distributions, or retirement plan loans.
Others impose stricter restrictions.
Your Summary Plan Description and NetBenefits account are important resources for understanding what is available.
The IRS explains that retirement plans may permit distributions only under applicable distribution rules and plan provisions.
Internal Revenue Service+1
Fidelity 401k Withdrawal After Leaving a Job
Changing employers is one of the most common reasons people reconsider their retirement savings.
When you leave a company, the money in your 401(k) does not automatically disappear.
Your vested retirement savings generally remain yours.
However, you need to decide how to manage them.
Leave the Money in Your Former Employer's Plan
Depending on the balance and plan rules, you may be able to keep your existing 401(k) account.
This can allow your investments to remain in a tax-advantaged retirement arrangement.
Before choosing this option, review investment choices, administrative fees, and minimum account balance requirements.
Transfer the Money to an IRA
Another option is to move eligible retirement savings into an Individual Retirement Account.
A direct rollover from a traditional 401(k) to a traditional IRA generally avoids immediate federal income taxation.
This option may be useful for people who want to consolidate retirement savings or explore different investment choices.
Transfer the Money to a New Employer's Plan
If your new employer offers a retirement plan that accepts rollovers, you may be able to move eligible funds into that account.
Consolidating plans can make retirement savings easier to monitor.
Compare investment expenses and plan features before transferring.
Cash Out Your Fidelity 401(k)
Some participants choose to withdraw their retirement savings as cash.
Although this provides access to money, it can create a significant tax burden and permanently reduce the amount invested for retirement.
Fidelity outlines these major options for employees leaving an employer and recommends reviewing vesting, taxes, fees, and retirement objectives before deciding.
Fidelity+1
How to Cash Out a Fidelity 401k?
A Fidelity 401k Cash Out means receiving an eligible retirement plan distribution as money rather than keeping the balance in a retirement account.
People commonly search for Cash Out 401k Fidelity when they have left a company, retired, or need money for personal expenses.
Understanding the Cash-Out Process
Begin by signing in to your Fidelity workplace retirement account.
Review your distribution eligibility and available vested balance.
If a cash distribution is permitted, follow the account's transaction instructions to request the amount you want.
Confirm your payment method and review the applicable tax withholding.
Once the transaction is approved and processed, the funds are sent using the available payment method.
Should You Withdraw the Entire Balance?
Withdrawing your full retirement balance may seem convenient, especially after leaving a job.
However, it can have long-term consequences.
A large taxable withdrawal may increase your taxable income for the year and potentially place part of your income in a higher tax bracket.
You may also lose years of possible tax-deferred investment growth.
If you only need a limited amount, check whether your plan permits a partial withdrawal instead of a complete cash-out.
Can You Transfer the Cash to Your Bank?
If the plan supports an electronic distribution to your bank account, eligible funds may be transferred using the payment instructions provided during the withdrawal process.
Payment availability and processing times depend on the plan, the type of withdrawal, verification requirements, and banking arrangements.
Do not assume the money will arrive immediately after submitting the request.
Fidelity 401k Withdrawal Hardship: Rules and Requirements
A Fidelity 401k Withdrawal Hardship may allow eligible employees to access a portion of their retirement savings because of an immediate and significant financial need.
A hardship distribution is different from an ordinary retirement withdrawal.
The employer-sponsored plan must permit hardship distributions, and the request must satisfy applicable IRS requirements.
What Qualifies for a Hardship Withdrawal?
The IRS recognizes several categories of expenses that can qualify as immediate and heavy financial needs under applicable hardship rules.
Examples include certain medical expenses, costs related to purchasing a primary residence, qualifying educational expenses, payments necessary to prevent eviction or foreclosure, funeral expenses, and certain home-repair expenses.
Qualifying disaster-related expenses may also be eligible under applicable rules.
However, an employer's plan can be more restrictive than the IRS rules.
A financial difficulty does not automatically qualify someone for a hardship distribution.
How to Apply for a Fidelity Investments Hardship Withdrawal
Start by opening your Fidelity NetBenefits account and reviewing the withdrawal options associated with your employer's plan.
If the plan offers hardship distributions, follow the displayed application process.
You may need to identify the reason for your request, enter the amount required, and provide information or supporting documents.
For example, someone requesting money for qualifying medical expenses may need to provide information about the expenses.
The plan administrator may request additional evidence before approving the distribution.
How Much Can You Withdraw for Hardship?
A hardship distribution must generally be limited to the amount necessary to satisfy the qualifying financial need.
The amount may include money needed to cover reasonably anticipated taxes and penalties associated with the withdrawal.
It is not necessarily equal to the entire retirement account balance.
Even when a participant has significant retirement savings, the available hardship amount may be limited by the plan's rules.
Does a Hardship Withdrawal Have to Be Repaid?
No. A hardship withdrawal is a distribution rather than a loan.
You generally cannot repay a hardship distribution to the plan or roll it over to another retirement account.
The distribution permanently reduces the balance unless future contributions and investment growth rebuild the account.
Hardship distributions may also be subject to income taxes and the 10% additional early withdrawal tax.
Under current IRS rules, plans cannot suspend employee elective contributions solely because someone received a hardship distribution after December 31, 2019.
See the IRS guidance on hardship withdrawals for the detailed eligibility and tax requirements.
Internal Revenue Service+1
Fidelity 401k Early Withdrawal: Taxes and Penalties
Before requesting an early distribution, it is essential to understand what you may owe.
Taking money from a traditional 401(k) before retirement may trigger ordinary income taxes and an additional early distribution tax.
Federal Income Tax on Withdrawals
Traditional pretax 401(k) withdrawals are generally included in taxable income.
The amount of tax depends on your overall financial circumstances, including other income, deductions, and filing status.
For instance, withdrawing money during a year when you already earn a substantial salary could result in a higher tax bill.
The 10% Early Withdrawal Tax
If you withdraw taxable retirement funds before age 59½, a federal 10% additional tax generally applies unless you qualify for an exception.
This additional tax is separate from ordinary federal income tax.
Certain exceptions include qualifying disability, some medical expenses, and eligible distributions after separation from employment at a qualifying age.
Understanding the Rule of 55
Under the IRS Rule of 55, someone who leaves an employer during or after the calendar year they reach age 55 may qualify for an exception to the 10% additional tax on distributions from that employer's eligible retirement plan.
This exception generally does not apply to distributions from an IRA.
The withdrawal may still be subject to ordinary income tax.
Check the precise requirements before relying on this exception.
Internal Revenue Service+1
Example of an Early Fidelity 401k Withdrawal
Consider someone who is 40 years old and wants to withdraw $10,000 from a traditional Fidelity 401(k).
Assume the entire withdrawal is taxable, the person falls within a 22% marginal federal income tax bracket, and no exception to the additional tax applies.
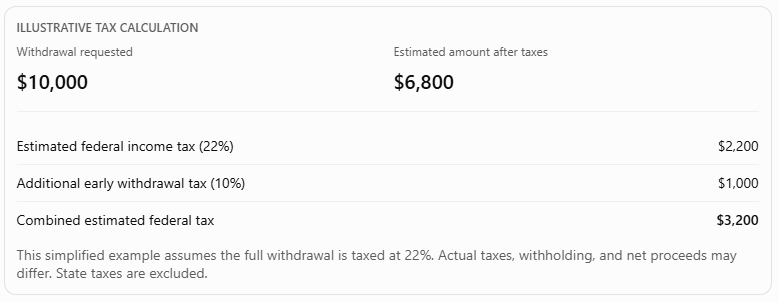
This example demonstrates why early withdrawals can be expensive.
Importantly, tax withholding is not the same as final tax liability. The money initially received may differ from the amount remaining after filing your tax return.
Fidelity 401k Withdrawal Tax Withholding
When requesting a distribution, participants should review how much money will be withheld for federal taxes.
For an eligible rollover distribution paid directly to the participant rather than directly rolled over, the IRS generally requires 20% federal income tax withholding on the taxable amount.
However, not every 401(k) withdrawal is an eligible rollover distribution.
Hardship distributions, for example, are not subject to the same mandatory 20% withholding rule. Different withholding provisions may apply.
The amount withheld may also be more or less than the taxes ultimately owed.
A direct rollover to another eligible retirement arrangement generally avoids mandatory withholding at the time of the rollover, although other tax considerations may arise depending on the destination account.
The IRS provides detailed guidance on these distinctions.
Internal Revenue Service+1
Fidelity 401k Withdrawal vs. 401(k) Loan
A withdrawal and a retirement plan loan are not the same transaction.
A withdrawal removes money from your retirement savings, and you generally do not repay it.
A 401(k) loan, when offered by your employer's plan, allows you to borrow against an eligible portion of the retirement account with a repayment obligation.
A properly administered and repaid loan generally does not create immediate taxable income.
However, missed repayments, default, or leaving employment can create complications and potential tax consequences.
Some people prefer a retirement plan loan because they intend to repay the amount instead of permanently withdrawing retirement savings.
Nevertheless, loans can reduce the amount of money invested while the borrowed funds are outstanding.
Not every plan offers loans, and restrictions may apply.
Fidelity recommends comparing available alternatives before deciding to borrow or withdraw from a workplace retirement plan.
Fidelity+1
How Long Does a Fidelity 401k Withdrawal Take?
The time required to complete a Fidelity 401k Withdrawal varies according to the transaction and the employer's retirement plan.
A straightforward eligible withdrawal may require fewer administrative steps than a hardship request involving supporting documents.
Several factors can affect processing.
Withdrawal Type
A regular retirement distribution, hardship request, or account cash-out may follow different review procedures.
Employer Plan Approval
Some transactions require the plan administrator to verify eligibility or review additional information.
If approval is necessary, processing may take longer.
Bank Verification
If electronic payment is available, Fidelity may need to verify the receiving account before transferring funds.
Incorrect or incomplete banking details can create delays.
Documentation Requirements
Hardship distributions may require additional information to establish the qualifying financial need.
Missing documents can delay a decision.
Payment Method
An electronic deposit and a mailed check can have different delivery times.
For the most reliable estimate, review the processing information displayed in NetBenefits or ask an authorized Fidelity workplace retirement representative about your specific transaction.
Fidelity 401k Withdrawal Phone Number and Customer Support
Some participants prefer speaking with a representative instead of completing retirement transactions entirely online.
People frequently search for terms such as Fidelity 401k Phone Number, Fidelity 401k Contact Number, Fidelity Investments 401k Phone Number, or Fidelity 401k Contact Phone Number.
The best place to find verified support details is Fidelity's official website or your workplace retirement account.
How to Contact Fidelity About a 401(k) Withdrawal
Visit the official Fidelity Contact Information page.
Look for the department covering workplace retirement plans, including 401(k), 403(b), and other employer-sponsored benefits.
You can also sign in to NetBenefits and locate the support details associated with your specific retirement plan.
Fidelity's official contact page lists a dedicated NetBenefits representative service for workplace retirement inquiries and publishes its current service hours.
Fidelity
Fidelity 401k Cash Out Phone Number
If you want help cashing out a retirement account, locate the official workplace retirement contact information rather than relying on phone numbers posted by unrelated websites.
A representative can explain the cash-out options available through your employer's plan.
They may also help you understand whether you need to submit a distribution request online or complete additional paperwork.
Fidelity Hardship Withdrawal Phone Number
Participants looking for a Fidelity Hardship Withdrawal Phone Number should use the official workplace retirement support channel shown on Fidelity's website or within NetBenefits.
Ask the representative whether the plan offers hardship withdrawals, what circumstances qualify, and whether documentation is required.
A representative can provide information about your available options, but approval remains subject to applicable plan and regulatory requirements.
Questions to Ask Fidelity Customer Service
Before contacting support, prepare a clear explanation of your situation.
You may want to ask whether you qualify for a withdrawal, how much is available, whether tax withholding applies, and how long the specific request may take.
If you are considering a hardship distribution, ask what documents are necessary.
For security, never share your password, verification codes, or complete account credentials with someone claiming to represent Fidelity through an unverified channel.
Why Is My Fidelity 401k Withdrawal Not Available?
Sometimes participants sign in to NetBenefits and discover that they cannot request a withdrawal.
Several circumstances may explain this issue.
You Are Still Employed
Some employer-sponsored retirement plans restrict ordinary withdrawals while participants are actively employed.
A qualifying event or specific in-service withdrawal provision may be necessary.
You Do Not Meet the Eligibility Requirements
Your age, employment status, reason for withdrawal, and the applicable plan rules determine which distributions are available.
Your Employer's Plan Has Restrictions
Even though Fidelity administers the account, the employer-sponsored plan may establish additional limits permitted under federal law.
The Available Balance Is Lower Than Expected
The displayed investment balance may differ from the amount eligible for withdrawal.
Unvested employer contributions, loan balances, or plan restrictions can affect the amount available.
The Request Needs Additional Review
A hardship or other special distribution may require supporting documents or administrative approval.
If a request is unavailable, review the Summary Plan Description and contact the appropriate workplace retirement support team before submitting another request.
Common Fidelity 401k Withdrawal Mistakes to Avoid
Taking money from a retirement account is an important financial decision. A mistake can lead to unnecessary taxes, delays, or reduced retirement savings.
One common mistake is withdrawing money without calculating the potential tax consequences. Some participants focus only on the amount they need and overlook the federal income tax and additional early withdrawal tax.
Another mistake is assuming a hardship withdrawal automatically avoids the 10% early distribution tax. A qualifying hardship does not, by itself, create an exception to that tax.
Participants should also avoid withdrawing their entire balance when a smaller eligible distribution would satisfy their financial needs.
Failing to compare a direct rollover with a cash withdrawal can be expensive, particularly after leaving an employer.
It is also important to confirm account details and payment information before submitting a transaction.
Finally, using unofficial customer support websites can expose sensitive retirement account information to fraud.
Always use trusted Fidelity websites and review the transaction carefully.
Alternatives to Withdrawing Money From a Fidelity 401(k)
Before making a withdrawal, consider whether another option could meet your financial needs without reducing your retirement savings.
If you have emergency savings, using part of those funds may be less expensive than triggering retirement withdrawal taxes.
Some participants may qualify for a 401(k) loan, although loans have repayment obligations and risks.
Others may benefit from reducing discretionary spending, arranging an eligible payment plan for necessary expenses, or exploring financial assistance programs.
If you recently changed employers, a direct rollover may preserve the tax advantages of your retirement funds.
The most suitable choice depends on your financial circumstances, available options, and long-term goals.
A qualified tax professional or financial adviser can help you compare the consequences of withdrawing retirement savings.
Frequently Asked Questions About Fidelity 401k Withdrawal
1. How do I get a Fidelity 401k Withdrawal?
Sign in to Fidelity NetBenefits, select your workplace retirement account, and look for available loans or withdrawal options. If you qualify, follow the instructions to enter the amount, review taxes, select an available payment method, and submit the request. Your plan determines which withdrawal options are offered.
2. Can I withdraw money from my Fidelity 401(k) while still employed?
Possibly. Some employer plans permit hardship withdrawals, in-service distributions, or other qualifying transactions. However, ordinary withdrawals may be restricted while you are actively employed. Review your plan's terms to determine eligibility.
3. How can I get a Fidelity Investments 401k Withdrawal after leaving my job?
After leaving an employer, you may generally request a distribution of your vested retirement savings, subject to plan processing requirements. You can also consider leaving the balance in the former employer's plan or completing an eligible rollover to an IRA or another employer's retirement plan.
4. Does a Fidelity 401k Hardship Withdrawal have a penalty?
A hardship withdrawal may be subject to ordinary income tax and the federal 10% additional tax if you are younger than 59½ and do not qualify for an exception. Financial hardship alone does not automatically eliminate the additional tax.
5. Where can I find the official Fidelity 401k Withdrawal Phone Number?
Visit Fidelity's official customer service website or sign in to NetBenefits to locate the appropriate workplace retirement support contact information. This is also the recommended approach when searching for a Fidelity 401k Cash Out Phone Number or hardship withdrawal assistance.
6. How long does it take to receive money from a Fidelity 401k withdrawal?
Processing times vary depending on the employer's plan, type of distribution, eligibility review, payment method, and verification requirements. Check your transaction status in NetBenefits or contact official workplace retirement support for a plan-specific estimate.
Conclusion
Getting a Fidelity 401k Withdrawal can be manageable when you understand your retirement plan's rules and follow the correct procedures.
The first step is to determine whether you qualify for a distribution. Your age, employment status, financial circumstances, and employer-sponsored plan conditions all affect eligibility.
If a withdrawal is permitted, you can generally begin by reviewing the available transaction options through Fidelity NetBenefits.
Before cashing out retirement savings, carefully consider income taxes, potential early withdrawal penalties, and the impact on your financial future.
For someone experiencing financial hardship, a qualifying withdrawal may provide access to needed money, but it can also permanently reduce retirement savings.
If you need help with a Fidelity Investments 401k Withdrawal, hardship application, or retirement account cash-out, use Fidelity's verified workplace retirement support channels.
Understanding your options and confirming the rules before submitting a request can help you make a more informed decision about your retirement savings.
Disclaimer: This article is for educational purposes only and is not personalized financial, tax, or legal advice. Withdrawal eligibility, tax treatment, and plan features can vary. Verify your plan's provisions and consult a qualified professional regarding your circumstances. This article is not affiliated with or endorsed by Fidelity Investments.
Fidelity 401k Withdrawal Phone Number and Customer Support
If you cannot complete your withdrawal online, Fidelity provides customer service for workplace retirement accounts.
You can verify the current Fidelity 401k withdrawal phone number and hours on Fidelity's official phone number directory.
How to Get Fidelity 401k Withdrawal Assistance
You can receive assistance by:
- Signing in to your NetBenefits account.
- Reviewing the plan's contact information.
- Calling the verified workplace retirement support number.
- Asking about withdrawal eligibility.
- Requesting information about required documents.
- Checking the status of a submitted request.
- Contacting your employer's benefits administrator when necessary.
Never provide your password, verification codes, or other sensitive login information to an unverified caller.
Resources
- All Categories
- 1.5K Atlanta Pro Community
- 92 Pro AI Hub
- 975 New Pro Hub
- 5 PAB & PPC corner
- 533 Trending topics
- 220 Feedback in Action
- 89 Wins and Recognition
- 21 Tools to help grow & run your business
- Pro Mentorship
- 274 Comunidad en Español
- 3 Featured Events
- 506 On-Demand Webinars
- 207 Network and Collaborate
- 361 Thumbtack Pro Rewards
- 1.9K Business Resources
- 280 Inspiration
- 168 Business Resilience
- 339 Thumbtack Resources
- 665 Community News
Welcome! Check out our Community Code of Conduct. (review here)